What is turning companies into fintechs?
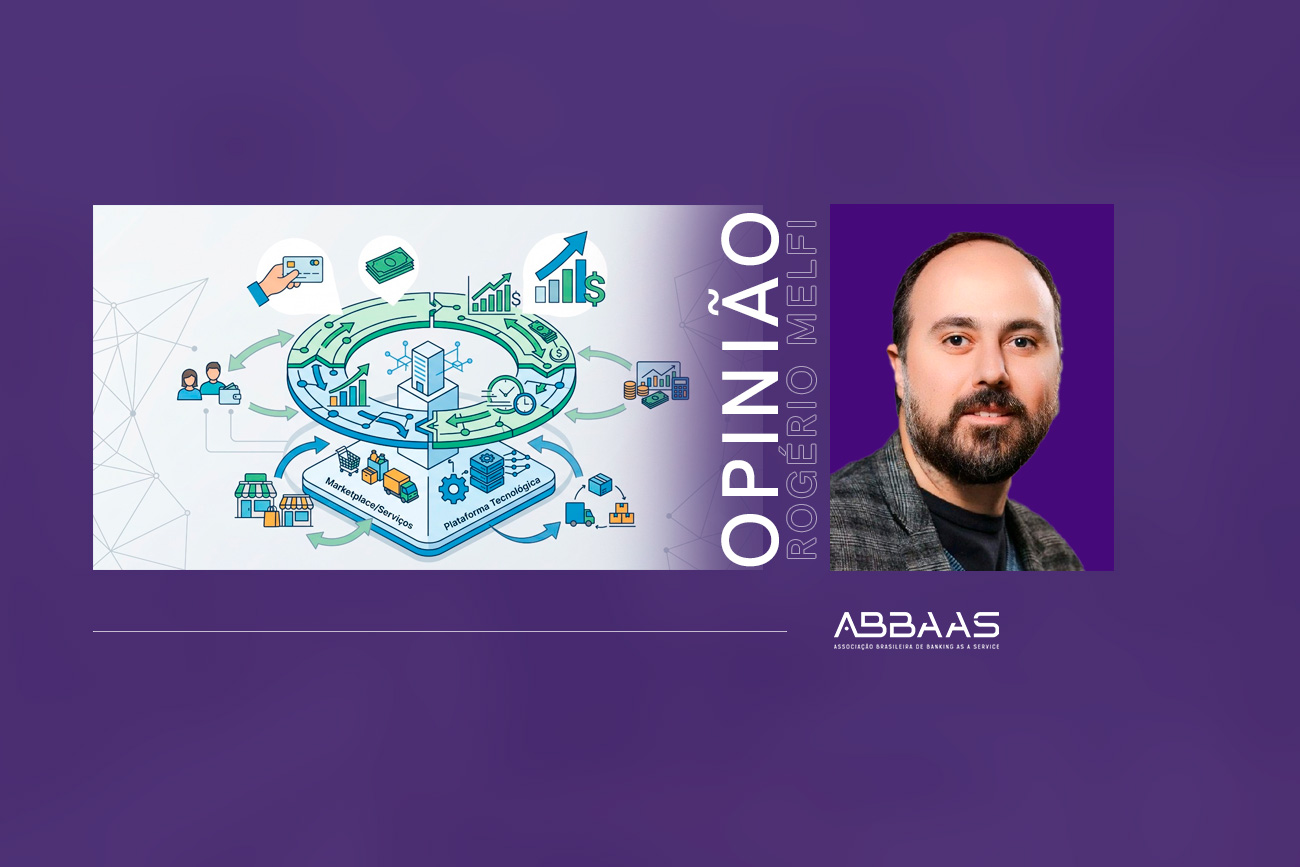
A shift is taking place in corporate strategy. Organizations that never aspired to become financial institutions have begun incorporating financial services as a central part of their operations. This is not simply product diversification. In many cases, finance has taken a structural role within the business model itself.
Digital platforms realized that payments, credit and financial flow management are not merely complementary services. They organize entire economic relationships within their ecosystems. When a company controls this financial layer, it directly influences the economic dynamics of its own network of users, suppliers or partners.
This phenomenon became more visible in digital marketplaces. By developing their own payment solutions, these platforms began organizing financial settlement between buyers and sellers. The next step was almost inevitable. If a platform already controls payment flows, it also gains the ability to offer credit, receivables advances and financial management tools to participants in its network. At that point, the nature of the business begins to change. The company stops being merely a digital intermediary and starts functioning as economic infrastructure within the ecosystem it created.
The same dynamic began appearing across various economic sectors. Mobility apps offer accounts for drivers. E-commerce platforms developed credit solutions for sellers. Business management software companies integrate payments and financial services directly into their systems.
In all these cases, the initial motivation was rarely to compete with banks. The goal was to resolve friction within the platforms themselves. Slow payment flows, difficulty accessing credit or inefficient financial management among business partners directly affect how these digital networks function. By incorporating their own financial solutions, companies reduce this friction and improve their ecosystems’ economic efficiency.
The result is a significant phenomenon. Financial services become infrastructure sustaining economic relationships within digital platforms. This process has often been associated with the advance of embedded finance. However, the transformation goes beyond incorporating financial services into apps or platforms. What is happening is a reorganization of these companies’ economic logic.
This change was possible only because financial infrastructure itself evolved profoundly in recent years. The spread of financial APIs, modernization of technological infrastructure and development of Banking as a Service (BaaS) models significantly reduced the complexity of integrating financial services into different digital platforms. Rather than building an entire banking structure internally, companies began connecting to existing infrastructure offering regulated access to accounts, payments, cards and other financial services. This new architecture allows companies to develop financial solutions faster and in alignment with their specific business model needs.
At the same time, it preserves the financial system’s institutional structure. Authorized institutions remain responsible for essential operational aspects. What changes is not the nature of the institutions, but how different digital economy platforms use this infrastructure.
Ultimately, what is turning companies into fintechs is not a change in institutional identity. It is a change in how economic value is organized within digital platforms. When payments, credit and settlement structure relationships within a digital ecosystem, the company stops operating solely as a technology platform. It begins functioning as the economic infrastructure of the network it connects.
And it is precisely at this point that many companies discover that, without necessarily planning to, they have become fintechs.
📌 Originally published in Inovativos